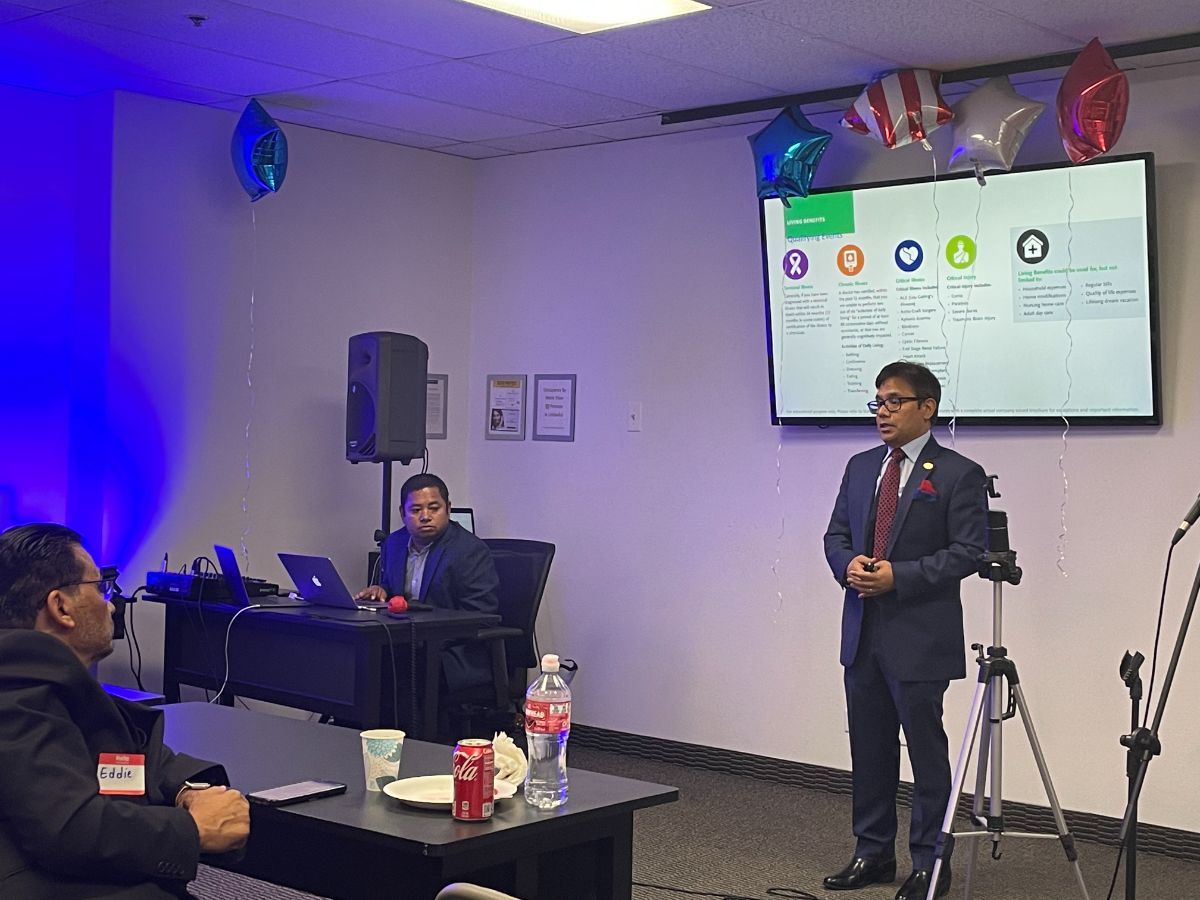
Many people do not like to talk about life insurance. In my community workshops, I can sometimes feel the room become quiet when the topic comes up, because it makes us think about something none of us wants to think about. I understand that feeling. But over the years I have come to see life insurance differently. It is not only about death — it is about love, responsibility and giving the people who depend on you a stable future. And today, many policies can also help you while you are still living.
Why Life Insurance Matters
At its heart, life insurance is a promise. You pay premiums, and if you pass away while the policy is in force, the insurance company pays a death benefit to the people you name as beneficiaries. That money can help your family in many practical ways:
- Replacing the income your family relies on
- Paying off a mortgage or other debts
- Covering children’s education costs
- Paying final expenses
- Giving your family time to grieve and adjust without rushing into difficult financial decisions
Life insurance matters most for anyone whose income or care supports someone else: parents, homeowners, business owners, and people helping aging parents or relatives. It also matters for a parent who stays at home, because the work that parent does would be costly to replace.
Term and Permanent Coverage, Simply Explained
There are two broad kinds of life insurance.
- Term life insurance provides coverage for a set period, such as the years when your children are young or your mortgage is being paid. If you pass away during that term, your beneficiaries receive the death benefit. If the term ends, coverage generally ends too, unless the policy allows you to renew or convert it. Term coverage is often the most affordable way to protect a growing family.
- Permanent life insurance, which includes types such as whole life and universal life, is designed to last for your lifetime as long as the policy stays in force. Many permanent policies also build cash value over time, which you may be able to access during your life. Permanent coverage usually costs more than term coverage for the same death benefit.
Neither type is better for everyone. It depends on what you are trying to protect, for how long, and what fits your budget. Some families use a combination. If you access cash value through a loan or withdrawal, it can reduce the death benefit and may have other consequences, so it is important to understand how your specific policy works.
Living Benefits: Protection While You Are Alive
This is the part many people have never heard about. Many modern policies include, or allow you to add, living benefits. These features may let you access part of your death benefit while you are still alive if you experience a qualifying chronic, critical or terminal illness.
Think about what a serious illness can do to a family. Even with good health insurance, there may be costs that health insurance does not cover, and there may be months when you cannot work. Living benefits can provide money during that difficult time, which may help with household bills, care at home or other needs.
A few important points to understand:
- Not every policy offers living benefits, and the features vary from one policy to another.
- Each policy defines which conditions qualify, so read those definitions carefully.
- Money you receive through living benefits generally reduces the death benefit your beneficiaries will receive later.
- There can be tax considerations, and receiving benefits could affect eligibility for some public programs, so it is wise to ask a tax professional about your situation.
How Much Coverage Might Your Family Need?
People often ask me for a simple rule. The honest answer is that it depends. Instead of starting with a number, start with your family’s needs. Some questions to consider:
- How many years would your family need your income replaced?
- What debts would you want paid off, including your mortgage?
- What education goals do you have for your children?
- What savings and existing coverage do you already have?
- Do you support parents or other relatives, here or abroad?
Many people have some life insurance through their employer, and that can be a helpful start. But workplace coverage may not be enough for a family’s full needs, and it may not stay with you if you change jobs or retire. It is worth knowing exactly what you have and what would happen to it if your work situation changed.
Your age and health also matter. In general, the younger and healthier you are when you apply, the more options you may have. Waiting does not make the decision easier, and changes in health can affect what is available later.
Common Misunderstandings
When I teach this topic, a few misunderstandings come up again and again. Clearing them up often helps people see life insurance in a new way.
- “I am young and healthy, so I do not need it yet.” Being young and healthy is often when coverage is easiest to qualify for. The question is not your age but whether someone depends on you.
- “My coverage at work is enough.” It may be a good foundation, but it is worth checking how much it provides and whether you could keep it if your job changed.
- “Life insurance is only for the breadwinner.” Every member of a household contributes something, and losing that contribution can create real financial strain.
- “Once I buy a policy, I am done.” Families change, and coverage that fit ten years ago may not fit today. A policy works best when it is reviewed from time to time.
None of these is a reason to feel pressure. They are simply reasons to look at your own situation honestly — with clear information, at your own pace.
Part of a Plan, Not Just a Product
I have always believed in knowledge before products. A life insurance policy should never be purchased in isolation, simply because someone made a good presentation. It should fit into your larger financial picture: your budget, your savings, your retirement goals, your health coverage and the people you want to protect.
The right policy is not the one with the most features. It is the one that fits your family’s needs, your budget and your long-term plan.
A good plan also needs care over time. Review your coverage when life changes, such as marriage, a new child, a new home, a new business or retirement. Keep your beneficiary designations up to date, and make sure a trusted family member knows where your policy documents are kept.
Life insurance is one of the most meaningful gifts you can give the people you love, and with living benefits, it can be a source of support for you as well. Take the time to understand your options without pressure. Please review your own situation with a licensed professional who will listen first and explain clearly. If you would like to start that conversation, Sagun Financials would be glad to help.