KNOWLEDGE · FINANCIAL EDUCATION
Financial Education
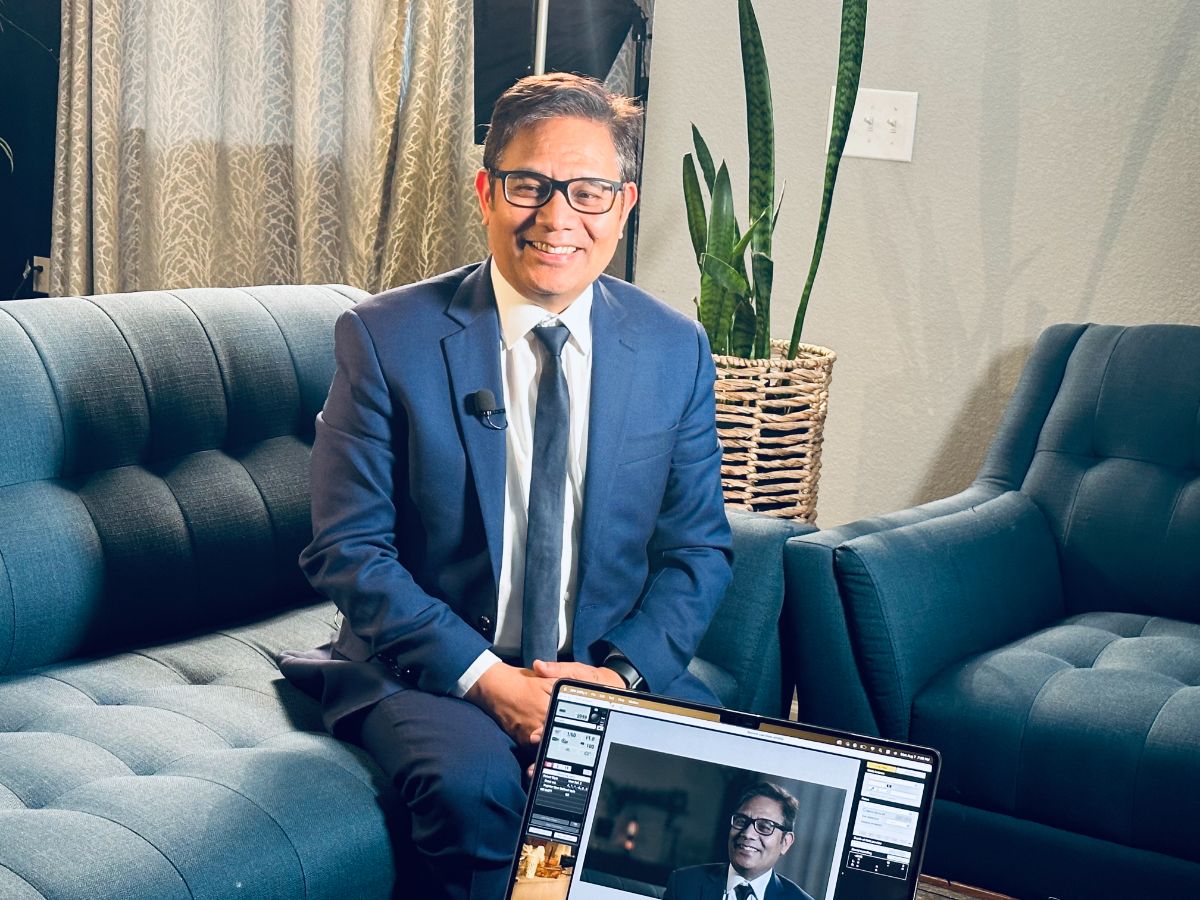
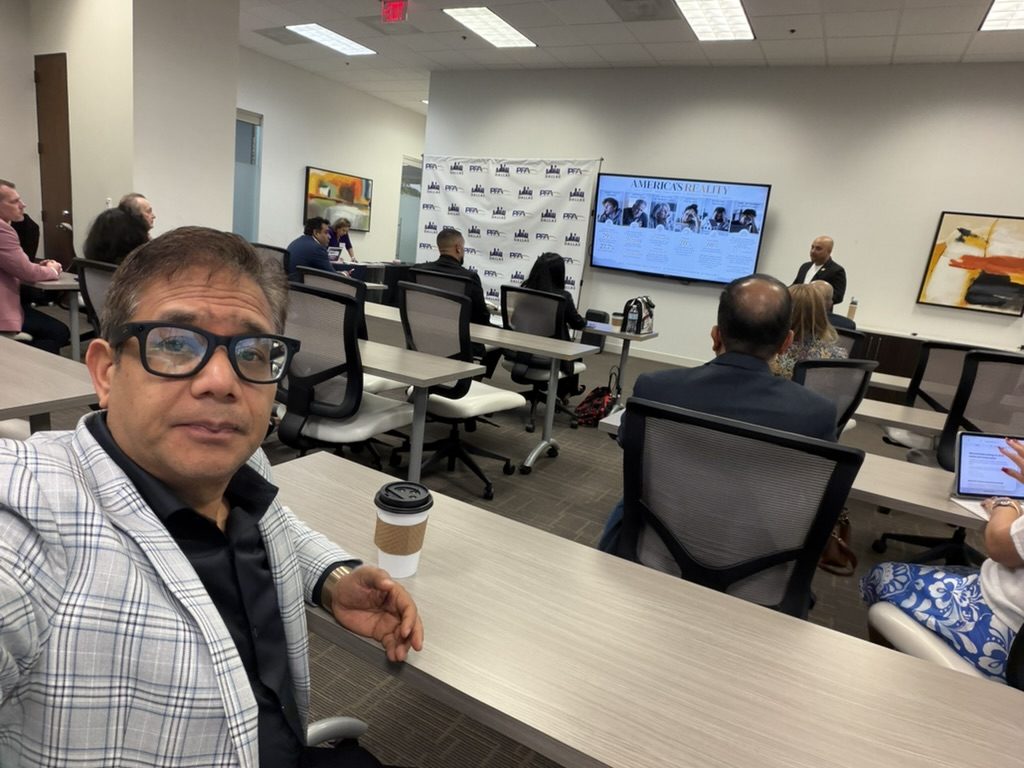
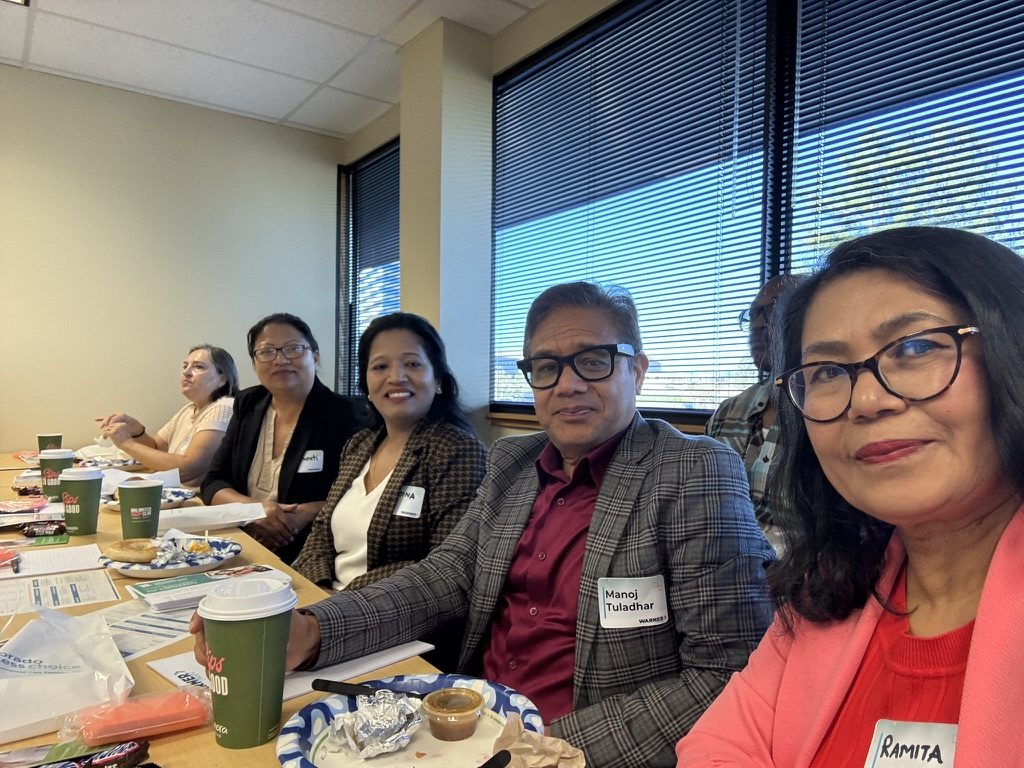
For more than a decade, I have taught financial education through workshops, seminars, community programs, and one-on-one conversations. This page shares the basics people ask me about most, in plain language, so you and your family can ask better questions and make decisions with confidence.
WHY IT MATTERS
Knowledge Before Products
After nearly two decades in banking and more than a decade in U.S. financial services, I have seen the same pattern again and again: people rarely make poor financial decisions because they don’t care. They make them because no one took the time to explain their options clearly.
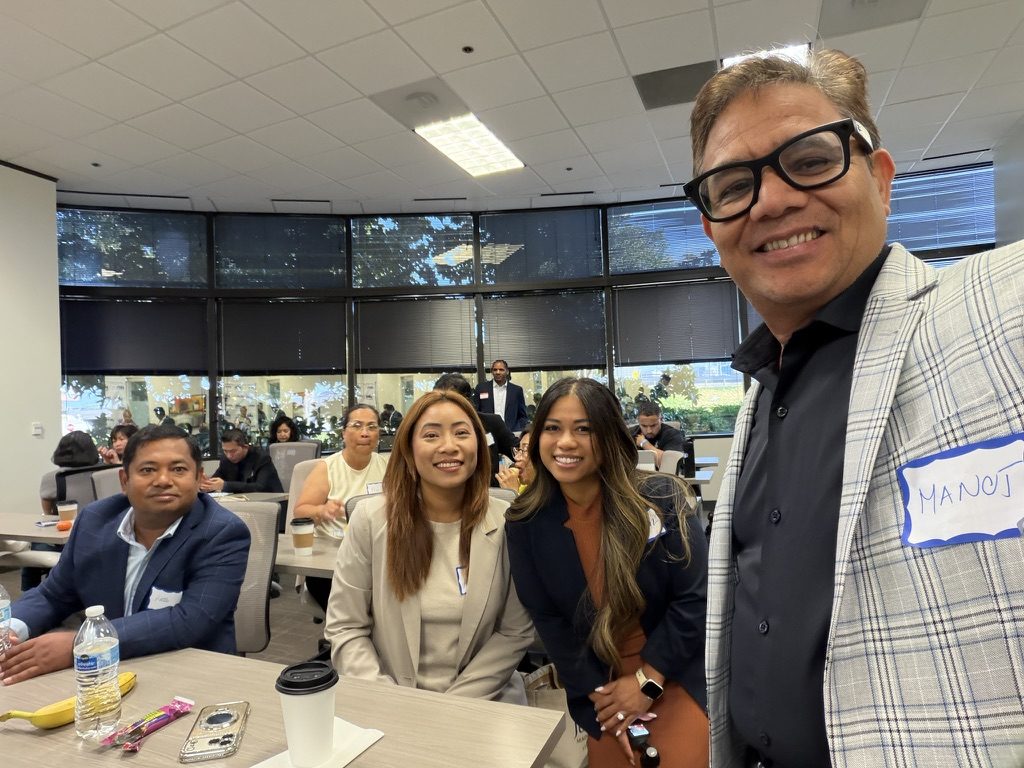
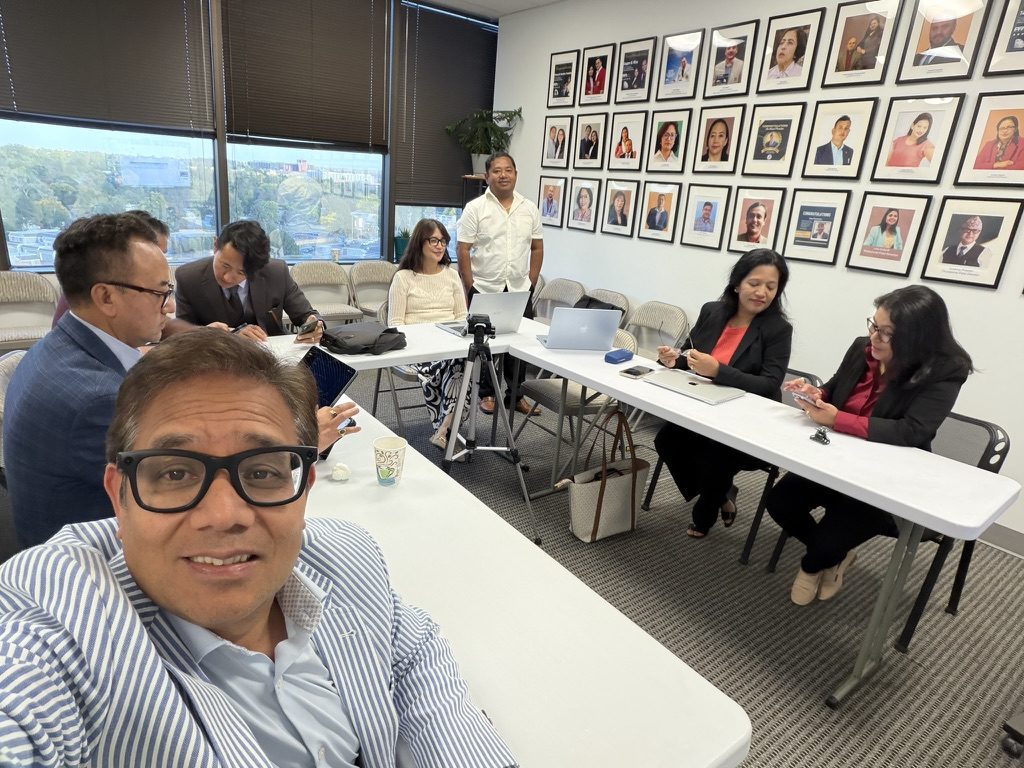
That is why I teach before I advise. In community workshops, family conversations, and training sessions, my goal is always the same: make complex ideas simple and practical, so people can make decisions that fit their own lives — not someone else’s sales goal.
MORE MOMENTS
Learning Together
01
Budgeting & Saving
For individuals, young families, and anyone starting fresh in a new country.
A budget is not about saying no to everything. It is a plan that tells your money where to go, so the things that matter most to you are paid for first and small leaks stop adding up.
KEY THINGS TO KNOW
Track every dollar for one month. Most people are surprised by where their money actually goes, and that picture is the starting point for every good plan.
Pay yourself first. Set up an automatic transfer to savings on payday, even a small amount, so saving happens before spending.
Build an emergency fund of three to six months of essential expenses, kept in a separate savings account you can reach quickly.
Want to learn this with your group?
02
Credit & Debt
For newcomers building U.S. credit, future homebuyers, and anyone paying down balances.
In the United States, your credit history affects the interest you pay on a car or a home, and sometimes whether you can rent an apartment. Good credit is built slowly, with simple habits repeated over time.
KEY THINGS TO KNOW
Paying on time and using only a small part of your available credit are the two biggest factors in most credit scores. Pay every bill on time and keep balances well below your limits.
To pay down debt, list every balance with its interest rate. Pay the minimum on all of them, then put every extra dollar toward one debt at a time: either the highest rate or the smallest balance.
You can check your credit reports from all three bureaus for free at AnnualCreditReport.com. Review them for mistakes at least once a year.
Want to learn this with your group?
03
Investing Basics
For beginners who want their savings to grow, and parents planning for a child’s future.
Saving keeps your money safe; investing helps it grow. Over long periods, steady investing has been one of the most dependable ways for ordinary families to build wealth, as long as they understand the risks and stay patient.
KEY THINGS TO KNOW
Start early. Because of compounding, money invested in your twenties or thirties has decades to grow, and time often matters more than the amount.
Spread your money across many investments, for example through low-cost index funds, so that no single company or market can sink your plan.
If your employer offers a 401(k) match, contribute at least enough to get the full match. It is one of the best returns available anywhere.
Want to learn this with your group?
04
Health Insurance
For individuals, families, self-employed professionals, and small businesses.
Health insurance protects you from the high cost of medical care, but choosing a plan involves more than comparing monthly premiums. Deductibles, out-of-pocket maximums, provider networks, and prescription coverage all affect what you will actually pay over a year.
KEY THINGS TO KNOW
In Colorado, individual Marketplace plans are offered through Connect for Health Colorado, and many households qualify for financial assistance that lowers monthly premiums.
Open Enrollment typically runs each fall into January. Outside that window, you may still enroll after a qualifying life event such as moving, marriage, a new baby, or losing other coverage.
Look at the total yearly cost — premium plus expected out-of-pocket spending — and confirm your doctors and medications are covered before choosing.
Have a question about your own situation?
05
Medicare
For people approaching 65, and anyone helping a parent or loved one with Medicare decisions.
Medicare is federal health coverage for people 65 and older and for some younger people with qualifying disabilities. It has several parts, and the choices you make when you first become eligible can affect your coverage and costs for years.
KEY THINGS TO KNOW
Your Initial Enrollment Period is a seven-month window around your 65th birthday — the three months before, your birthday month, and the three months after.
Original Medicare (Parts A and B) can be paired with a Medicare Supplement and a Part D drug plan, or you can choose an all-in-one Medicare Advantage plan. Each approach has trade-offs.
The Annual Enrollment Period, October 15 to December 7, is the time to review your plan each year, because benefits, networks, and drug coverage can change.
Have a question about your own situation?
06
Life Insurance
For parents, homeowners, business owners, and anyone whose income supports someone else.
Life insurance is one of the most important ways to protect the people who depend on you. The right policy can replace income, pay off debt, cover education costs, and give your family time to adjust after a loss.
KEY THINGS TO KNOW
Term life insurance provides coverage for a set period and is often the most affordable way to protect a growing family.
Permanent life insurance can last for life and may build cash value over time.
Many modern policies include living benefits that may let you access part of the death benefit if you experience a qualifying chronic, critical, or terminal illness.
Have a question about your own situation?
07
Retirement Strategies
For working professionals, pre-retirees, and retirees thinking about income.
Retirement planning is not only about how much you save. It is also about turning those savings into dependable income that can last as long as you do, while managing risks like market downturns, inflation, and rising healthcare costs.
KEY THINGS TO KNOW
Start by estimating your retirement expenses and the income you can expect from Social Security, pensions, and savings.
Some annuities can provide guaranteed income for life or protect a portion of your savings from market losses. They are not right for everyone, so fees, surrender periods, and terms deserve careful review.
When changing jobs or retiring, understand your rollover options before moving money from an employer retirement plan.
Have a question about your own situation?
RESOURCES
Downloads
Free checklists and worksheets to help you prepare before your next financial conversation.
BUDGETING
Monthly Budget Worksheet
List your income and expenses for the month and see exactly where your money goes.
CREDIT & DEBT
Debt Payoff Planner
List every balance and rate, choose a payoff order, and track your progress.
INVESTING
Investing Starter Checklist
Questions to answer and steps to take before your first investment.
HEALTH INSURANCE
Health Plan Comparison Worksheet
Compare premiums, deductibles, out-of-pocket maximums, and networks side by side.
MEDICARE
Turning 65: Medicare Checklist
Key dates, documents, and questions to prepare before your Initial Enrollment Period.
MEDICARE
Annual Medicare Review Checklist
What to check each fall before the Annual Enrollment Period.
LIFE INSURANCE
Family Protection Needs Worksheet
Estimate how much coverage your family may need.
RETIREMENT
Retirement Income Planning Worksheet
Map expected expenses against Social Security, pensions, and savings.
ORGANIZATION
Family Financial Organizer
Keep policies, accounts, and important contacts in one place for your loved ones.
FAQ
Frequently Asked Questions
Yes. I lead financial education workshops and seminars for community groups, cultural organizations, workplaces, and families. Topics range from budgeting, saving, and credit to insurance, Medicare, and retirement.
Yes. Sessions can be held in English or Nepali, and many community programs use both, so every generation in the family can follow along.
Yes. Workshops and conversations can take place in person in Colorado or online by video, whichever works best for you or your group.
A common goal is three to six months of essential expenses: housing, food, utilities, transportation, and minimum debt payments. If your income is irregular or you support family, aim for the higher end. Start with a smaller first goal, such as $1,000, and build from there.
Try the 50/30/20 guideline as a starting point: about half of your take-home pay for needs, 30 percent for wants, and 20 percent for saving and paying down debt. Adjust the numbers to fit your life; the habit matters more than the exact split.
Start with a secured credit card or a credit-builder loan from a bank or credit union, use it for one small regular bill, and pay it in full every month. Being added as an authorized user on a family member’s card can also help. Most people can build a score within six months to a year.
Usually both. Build a small emergency fund first, so a surprise expense does not go on a credit card, then put extra money toward high-interest debt. Once a debt is paid off, move that same payment into savings and investing.
No. Checking your own credit report or score does not affect it. Your score can dip slightly when you apply for new credit, so apply only when you need it.
Much less than most people think. Many retirement accounts and index funds let you begin with small, regular contributions. Starting early and staying consistent matters more than starting big.
Open Enrollment typically takes place each fall and runs into January. If you experience a qualifying life event — such as moving, getting married, having a baby, or losing other coverage — you may be eligible for a Special Enrollment Period.
Eligibility depends on your household size, income, and other factors. Many individuals and families qualify for premium tax credits that lower their monthly cost. Connect for Health Colorado can show you what you may qualify for.
Ideally three to six months before you turn 65. Your Initial Enrollment Period begins three months before your birthday month, and planning ahead helps you avoid gaps in coverage or late-enrollment penalties.
Medicare Advantage plans replace Original Medicare with an all-in-one plan, often with networks and additional benefits. Medicare Supplements work alongside Original Medicare to help pay costs it does not cover and usually let you see any provider who accepts Medicare. The right choice depends on your health, budget, doctors, and travel needs.
Yes, during certain periods. The Annual Enrollment Period runs October 15 to December 7 each year, and there is a Medicare Advantage Open Enrollment Period from January 1 to March 31. Some situations also qualify for special enrollment.
It depends on your income, debts, family needs, and goals. A common starting point is to consider how many years of income your family would need replaced, plus major obligations like a mortgage or education costs.
Living benefits are features in some life insurance policies that may allow you to access part of your death benefit while you are still alive if you experience a qualifying chronic, critical, or terminal illness.
Annuities can be useful for creating guaranteed income or protecting savings from market losses, but they are long-term products with specific terms. Before deciding, review your goals, timeline, fees, and how soon you may need the money, ideally with a licensed professional.
Want a workshop for your group or community?
Have a Question That Isn’t Here?
Send me your question, or invite me to speak with your group. If it is about your own coverage, I will point you to the right licensed professional.
IMPORTANT INFORMATION
The information on this page is provided for general educational purposes only and is not legal, tax, investment, or individualized financial or insurance advice. Plan availability, benefits, costs, and enrollment rules vary by carrier, location, and individual circumstances and may change. Please consult a licensed professional about your specific situation.